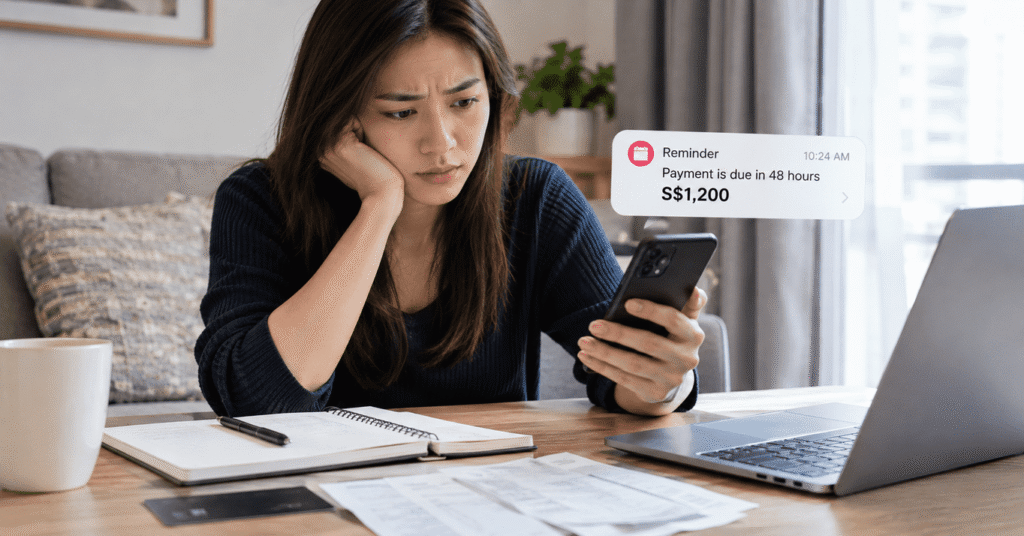
The reminder says S$1,200. Your available balance says S$450. Salary arrives next week, but the deadline is Friday.
Before searching for an urgent cash loan today, establish whether you need the full bill covered or just the S$750 difference. Then check when the recipient must actually receive the funds. An approved application does not settle an invoice until the transfer reaches its destination.
A useful funding decision starts with three questions: what is the exact shortfall, which route can meet the deadline, and how will you repay?
Facing A Payment Deadline? Key Funding Options To Explore
1. Negotiate a revised deadline or split settlement.
Start with the organisation expecting the money. A landlord, clinic or service provider may accept part now and the remainder on an agreed date. This could reduce or remove the need for borrowing, although acceptance is never automatic.
Make a specific proposal: S$450 before Friday, followed by S$750 after salary arrives. Ask whether late charges, service restrictions or collection action would still apply. Obtain written confirmation rather than relying on a telephone assurance.
This route is especially useful when incoming earnings are confirmed. If the deadline cannot move, establish the minimum sum required to prevent the immediate consequence before exploring credit
2. Request an employer advance or documented family support.
Ask your payroll team if a salary advance is possible, how soon it can be arranged and how the amount will be recovered. This depends on company policy; it is not an entitlement.
Calculate your remaining take-home pay after recovery. An advance that leaves insufficient money for rent or transport simply moves the problem into another week.
Alternatively, a relative may offer temporary help. Record the sum, transfer date, repayment deadline and any agreed interest in writing. Clear terms protect the relationship and prevent different expectations. Avoid promising repayment from overtime, commissions or bonuses that have not yet been confirmed.
3. Check an existing bank credit facility.
An already approved personal line of credit may provide access without starting a completely new application. Confirm your available limit, withdrawal method and when the transfer will arrive.
Revolving facilities commonly charge interest according to usage. For example, DBS Cashline calculates interest daily from the transaction date until full repayment, subject to its applicable minimum charge. Ask for the cost of your intended borrowing period, including withdrawal or transfer fees. A balance cleared after seven days may cost differently from one carried for several months.
Set a definite clearance date. Repeatedly paying only the minimum can leave the principal outstanding and keep charges running.
4. Consider a bank personal instalment loan.
A fixed repayment schedule may suit a necessary expense that cannot comfortably be cleared from one pay cheque. However, a fresh application introduces eligibility checks and processing requirements.
Treat personal loan fast approval as a search phrase, rather than a promise of funds before your deadline. Confirm whether the stated timeframe applies to all applicants or only to existing customers and selected account holders. Compare the effective interest rate, processing charge, total repayable and early settlement conditions. Ask when the first instalment falls due.
Borrowing more merely to qualify for a promotion increases the debt. Request only the amount needed and ensure each scheduled deduction fits after essential household spending.
5. Assess borrowing through licensed moneylenders.
When comparing fast cash loans in Singapore, check the provider against the Registry of Moneylenders’ official list. Match both the website and approved business address. Singapore requires physical, face-to-face identity verification at approved premises before granting the facility; a fully online transaction is prohibited.
These licensed moneylenders can charge up to 4% monthly interest on the outstanding principal and an upfront approval fee capped at 10% of principal. Check the net proceeds. A S$1,000 facility with a S$100 upfront deduction leaves S$900 available, which would not cover a S$1,000 invoice. Compare written offers using both the amount received and the full contractual repayment schedule.
6. Explore pawnbroking against an asset you own.
A licensed pawnbroker may lend against an accepted valuable, such as gold jewellery. The offer depends on its valuation, so the original purchase price does not establish how much you will receive.
Singapore caps pawnbroking interest at 1.5% monthly, with a six-month redemption period that may be extended by agreement. Read the pawn ticket and understand the forfeiture process.
Choose this only if you can accept losing the pledged item should redemption become unaffordable. Sentimental jewellery deserves particular care. Selling an unused possession is another possibility, but buyer availability and settlement timing make an unconfirmed sale unreliable for a firm deadline.
7. Use a credit card only after checking transaction costs.
If the recipient accepts cards, direct settlement may avoid withdrawing cash. Check merchant surcharges and whether your account qualifies for an interest-free period.
A cash advance works differently: fees apply, and interest generally starts immediately. Do not assume the usual purchase grace period applies.
Before using either route, check how the new balance changes your next statement. Covering an invoice today is unhelpful if the resulting card bill becomes unmanageable.
When comparing this route with fast cash loans in Singapore, use the same sum and realistic repayment date. Compare total cost rather than a monthly percentage against an annual headline rate.
Conclusion:
Responsible lending should give you clarity when urgency makes it harder to think. When comparing licensed moneylenders, expect a clear explanation of what you will receive, what you will owe and when each instalment falls due. At Fast Money, we believe speed is valuable only when the repayments fit comfortably within your budget. If you are exploring quick loans in Yishun and Tampines, speak to us about your deadline, required amount and current commitments. We can assess your application and explain the proposed terms before you decide.

